The 401k Limits 2026 are the annual contribution limits set by the Internal Revenue Service (IRS) for employees and employers participating in 401(k) retirement savings plans. For 2026, employees can contribute up to $24,500 to a traditional or Roth 401(k), an increase of $1,000 from 2025. Workers aged 50 and older can generally contribute an additional $8,000, while those aged 60 through 63 qualify for a higher catch-up contribution of $11,250.
The combined employee and employer contribution limit also increases to $72,000, excluding eligible catch-up contributions.
These changes create additional retirement savings opportunities, but there’s more to understand than the headline numbers. New Roth catch-up requirements, employer matching rules, and age-based contribution limits can affect how much you save and how your contributions are taxed.
I’ll explain what changed, who qualifies, and how to make the most of the 2026 limits.
What Are the New 401k Contribution Limits for 2026?
The IRS adjusts retirement contribution limits periodically to account for inflation and changes in the cost of living.
For 2026, both employee contribution limits and total annual contribution limits have increased.
Here’s how the new limits compare with 2025.
| Contribution Category | 2025 Limit | 2026 Limit |
|---|---|---|
| Employee contribution limit | $23,500 | $24,500 |
| Catch-up contribution, ages 50–59 and 64+ | $7,500 | $8,000 |
| Higher catch-up contribution, ages 60–63 | $11,250 | $11,250 |
| Maximum employee contribution, under age 50 | $23,500 | $24,500 |
| Maximum employee contribution, ages 50–59 and 64+ | $31,000 | $32,500 |
| Maximum employee contribution, ages 60–63 | $34,750 | $35,750 |
| Combined employee and employer limit, excluding catch-ups | $70,000 | $72,000 |
| Annual compensation limit | $350,000 | $360,000 |
Source: IRS retirement contribution limits and cost-of-living adjustments.
The most noticeable change for younger workers is the additional $1,000 in annual contribution capacity.
For employees approaching retirement, the opportunity is larger. Workers eligible for regular catch-up contributions can now contribute $32,500 annually, assuming their plan permits it.
One detail I always emphasize is that these figures represent maximums, not mandatory savings amounts.
You can contribute less based on your income, household expenses, and retirement goals.
How Much Can Employees Contribute to a 401k in 2026?
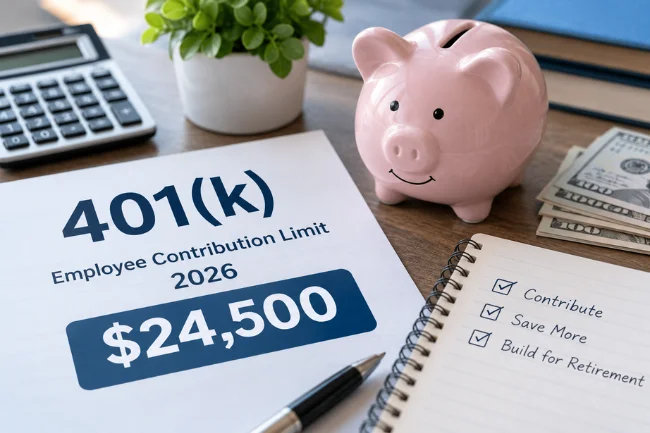
The standard 401(k) employee contribution limit for 2026 is $24,500.
This applies to eligible employees participating in traditional 401(k) plans, Roth 401(k) arrangements, and most employer-sponsored 401(k) retirement plans.
Traditional and Roth 401k Contributions Share One Limit
A common misconception is that traditional and Roth 401(k) accounts have separate contribution allowances.
They don’t.
The $24,500 limit applies to the combined amount you contribute to both accounts.
For example, you could contribute:
- $15,000 to a traditional 401(k).
- $9,500 to a Roth 401(k).
Your combined contribution would equal $24,500, reaching the standard annual limit.
You cannot contribute $24,500 to each account separately.
The same principle generally applies when you participate in multiple employers’ 401(k) plans during the year.
Does Your Salary Affect the Limit?
Your compensation and your employer’s plan rules can affect how much you’re allowed to contribute.
For instance, someone earning $45,000 may be legally eligible for the $24,500 maximum but might not be financially comfortable saving more than half their annual salary.
Highly compensated employees may also face plan-specific restrictions resulting from nondiscrimination testing.
I recommend reviewing the plan’s summary plan description rather than assuming the IRS maximum is automatically available to everyone.
401k Catch-Up Contribution Limits for 2026
Catch-up contributions allow older workers to save additional money beyond the standard annual contribution limit.
They’re particularly useful for people who started saving later, experienced career interruptions, or want to increase retirement contributions during higher-earning years.
Employees Aged 50 to 59
Workers who turn 50 or older by December 31, 2026, may qualify for an additional $8,000 contribution.
Their maximum employee contribution becomes:
$24,500 + $8,000 = $32,500.
This catch-up allowance is available regardless of whether you are actually behind on retirement savings.
Employees Aged 60 to 63
The SECURE 2.0 Act introduced a higher catch-up limit for workers who reach ages 60, 61, 62, or 63 during the calendar year.
In 2026, that special allowance is $11,250.
Their maximum employee contribution is:
$24,500 + $11,250 = $35,750.
The $11,250 replaces the standard $8,000 catch-up allowance; it isn’t added on top of it.
What Happens at Age 64?
The special catch-up allowance ends when you reach age 64.
At that point, the regular age-50-plus catch-up limit applies again, making the 2026 maximum $32,500.
This age-based change deserves attention when planning contributions around retirement.
You can confirm eligibility through the IRS catch-up contribution guidance.
New Roth 401k Catch-Up Rules Starting in 2026
One of the biggest 401(k) changes for 2026 concerns how certain higher-income workers must make catch-up contributions.
Under the SECURE 2.0 Act, employees whose 2025 FICA wages from the employer sponsoring their plan exceeded $150,000 generally must make their 2026 catch-up contributions on a Roth basis.
That means the required catch-up contributions are made with after-tax money rather than through traditional pre-tax salary deferrals.
Who Is Affected?
Consider an employee who earned $165,000 in FICA wages from the plan sponsor in 2025 and turns 55 during 2026.
The employee can generally contribute:
- $24,500 through traditional or Roth 401(k) contributions.
- Another $8,000 in catch-up contributions, which must be Roth contributions.
The requirement applies to the catch-up portion, not necessarily the entire annual contribution.
Employees who did not exceed the $150,000 prior-year wage threshold generally retain the option to make pretax catch-up contributions if their plans allow them.
Why the Previous Year’s Wages Matter
The rule uses eligible FICA wages from 2025, not your projected 2026 salary.
It also isn’t based simply on household income or your federal income tax bracket.
Someone who changes jobs or receives substantial self-employment income may face a different outcome because the rule considers wages from the employer sponsoring the retirement plan.
Employers must administer the requirement under applicable rules, so I suggest confirming your eligibility and payroll settings with your benefits department.
If a plan lacks the required Roth feature, affected participants may be unable to make catch-up contributions through that plan.
Maximum 401k Contributions in 2026 Including Employer Match
The employee contribution limit and the combined employee-employer limit are two different numbers.
In 2026, the overall annual additions limit is generally the lesser of:
- $72,000.
- 100% of eligible compensation.
This limit includes regular employee deferrals, employer matching contributions, employer nonelective contributions, and other amounts counted under IRS rules.
Eligible catch-up contributions are excluded from the standard $72,000 ceiling.
That creates the following potential combined totals:
- Under 50: $72,000.
- Ages 50–59 and 64+: $80,000.
- Ages 60–63: $83,250.
These are legal ceilings, not amounts every employee can necessarily contribute. Reaching them depends on compensation, employer contributions, and plan features.
Example: How an Employer Match Affects Your Total
Suppose you’re 40 years old and earn $120,000 annually.
You contribute the full $24,500, while your employer contributes $6,000.
Your retirement account receives $30,500 in total contributions.
You’re still below the $72,000 combined limit, but you’ve already used your entire regular employee salary-deferral allowance.
Any additional contributions would need to qualify under another permitted contribution category.
This distinction matters when comparing employer-sponsored retirement benefits.
Traditional vs. Roth 401k: Which Makes More Sense in 2026?
The contribution limits are generally the same for traditional and Roth 401(k) savings.
What changes is the tax treatment.
Traditional 401k: Tax Savings Today
Traditional pretax 401(k) contributions reduce your federal taxable income for the year in which you contribute.
For example, a $10,000 pretax contribution could reduce federal income tax by approximately $2,400 if the entire deduction offsets income taxed at a 24% marginal rate.
That is an illustration, not a guaranteed tax saving.
Traditional contributions are generally still subject to Social Security and Medicare taxes.
Withdrawals of pretax contributions and their earnings are generally taxable during retirement.
Roth 401k: Potential Tax Savings Later
Roth contributions are made using after-tax income.
You don’t receive the same upfront income tax reduction, but qualified retirement withdrawals, including eligible investment earnings, are tax-free.
I would compare my current marginal tax rate with my expected retirement tax situation before choosing between the two.
Someone expecting higher tax rates later may favor Roth contributions, while someone expecting lower rates in retirement may prefer traditional contributions.
A combination of both can also provide more flexibility.
How Much Should You Contribute Per Paycheck in 2026?
Knowing the annual maximum is useful, but converting it into a payroll amount makes retirement planning more practical.
For employees receiving 26 biweekly paychecks, the amounts look like this:
| Employee Age | Annual Maximum | Approx. Per Paycheck |
|---|---|---|
| Under 50 | $24,500 | $942.31 |
| 50–59 or 64+ | $32,500 | $1,250 |
| 60–63 | $35,750 | $1,375 |
These examples assume contributions are spread evenly across all 26 paychecks and the employee is eligible for the relevant maximum.
If you’re under 50 and paid monthly, you would need to contribute approximately $2,041.67 per month to reach $24,500.
Why Payroll Timing Matters
One practical issue I pay attention to is when contributions actually begin.
If you wait until the middle of the year to increase your contribution rate, reaching the annual maximum may require significantly larger deductions from your remaining paychecks.
Bonuses can also affect your contribution strategy if your employer allows retirement deductions from bonus payments.
Rather than relying on one fixed percentage, I recommend calculating the remaining contribution target using your actual pay schedule and year-to-date savings.
Does the Employer Match Count Toward the 2026 Employee Limit?
No. Employer matching contributions do not count toward your personal $24,500 elective deferral limit.
They do, however, count toward the overall $72,000 annual additions ceiling.
Suppose your employer matches 50% of your contributions up to 6% of your salary.
If you earn $100,000 and contribute at least $6,000, your employer would contribute $3,000 under that formula.
That employer contribution is additional retirement savings without requiring you to reduce your own annual deferral allowance.
Watch Out for the Early-Maximum Problem
Reaching your 401(k) maximum too early in the year can sometimes cause you to miss employer matching contributions on later paychecks.
Some plans match contributions each pay period, while others offer a year-end true-up contribution.
A true-up can compensate eligible employees whose uneven contributions would otherwise reduce their annual match.
Before accelerating contributions, I would check whether the plan has a true-up provision and whether any eligibility conditions apply.
It’s a small administrative detail that can have real financial consequences.
What Happens If You Have Two 401k Plans in 2026?
Changing jobs doesn’t give you a fresh $24,500 employee contribution limit.
Your elective salary deferrals to 401(k) plans generally share one annual individual limit, even when different employers sponsor the accounts.
Imagine contributing $14,000 to your previous employer’s 401(k) before changing jobs.
You would normally have just $10,500 of regular elective deferral capacity remaining in 2026.
The new employer’s payroll system may not automatically know what you contributed elsewhere.
That makes tracking both plans essential.
What If You Contribute Too Much?
If you exceed the applicable employee deferral limit, you should notify the plan administrator and request a corrective distribution.
For 2026 excess deferrals, the IRS generally requires the excess and applicable earnings to be distributed by April 15, 2027, to avoid potentially unfavorable tax consequences.
The deadline is not extended simply because you obtain a tax-filing extension.
One additional distinction: eligible governmental 457(b) plans generally have a separate deferral limit, which can create different savings opportunities for employees who have access to both plan types.
Solo 401k and SIMPLE 401k Limits for 2026
Business owners and self-employed individuals need to understand that not every plan with “401(k)” in its name follows identical contribution rules.
Solo 401k Contribution Limits
A solo 401(k) is generally intended for a business owner without employees other than an eligible spouse.
The owner can contribute as both employee and employer.
For 2026, the regular employee deferral limit is $24,500, while total annual additions can reach $72,000, excluding permitted catch-up contributions.
However, employer contributions depend on business income, compensation calculations, and applicable contribution formulas.
Self-employed individuals must account for adjustments involving self-employment taxes and net earnings.
I wouldn’t assume that having a profitable business automatically makes the full $72,000 available.
The IRS solo 401(k) guidance explains these calculations.
SIMPLE 401k Contribution Limits
SIMPLE 401(k) plans have lower employee contribution limits.
For 2026, the standard employee contribution limit is $17,000.
Eligible employees aged 50 and older can generally make an additional $4,000 catch-up contribution.
Employees aged 60 through 63 qualify for a higher catch-up amount of $5,250.
Different rules may apply to certain SIMPLE arrangements, so participants should verify their specific plan provisions.
Can You Contribute More Than $24,500 Using After-Tax Savings?
Potentially, yes.
Some employer plans permit voluntary after-tax employee contributions beyond regular pre-tax and Roth elective deferrals.
These contributions are different from designated Roth 401(k) salary deferrals.
They generally count toward the $72,000 annual additions limit rather than the standard $24,500 elective deferral ceiling.
For example, suppose you contribute $24,500 and your employer adds $9,000.
That leaves $38,500 of room beneath the $72,000 overall ceiling, assuming sufficient compensation and no other annual additions.
If the plan allows additional after-tax contributions, some of that remaining capacity might be available.
Certain plans also support conversions associated with the strategy commonly called a mega backdoor Roth.
These strategies require careful attention to plan rules and tax consequences. They aren’t available in every 401(k).
How to Make the Most of the 401k Limits 2026
The higher 2026 limits are useful only when they support a realistic savings plan.
Here’s how I would approach the decision.
Prioritize the Available Employer Match
If your employer offers matching contributions, review the formula and contribute enough to capture the full available benefit whenever financially practical.
Also check vesting schedules and whether the match is calculated annually or per paycheck.
Increase Contributions Gradually
You don’t have to reach the annual maximum immediately.
Increasing contributions by one or two percentage points when you receive a raise can be a manageable way to improve retirement savings.
For someone earning $80,000, an additional 1% contribution represents $800 annually.
Review Other Retirement Accounts
A 401(k) isn’t necessarily your only retirement savings option.
For 2026, the IRA contribution limit is $7,500, with an additional $1,100 catch-up contribution for eligible savers aged 50 and older.
IRA contributions have separate limits, and income-based restrictions may affect deductible traditional IRA contributions and direct Roth IRA eligibility.
Revisit Your Investment Allocation
Contribution limits control how much money enters the plan, not how it is invested.
I would also review investment expenses, asset allocation, diversification, and the number of years remaining until retirement.
A higher savings rate helps, but choosing an appropriate investment strategy remains essential.
Common 401k Contribution Mistakes to Avoid in 2026
Even experienced retirement savers can misunderstand annual contribution rules.
Some mistakes worth watching for include:
- Treating traditional and Roth 401(k) contribution limits as separate allowances.
- Forgetting to combine employee deferrals made through different employers.
- Assuming employer matching contributions reduce the personal salary-deferral limit.
- Overlooking the new Roth catch-up requirement for certain higher earners.
- Assuming everyone aged 50 or older qualifies for the special ages-60-to-63 catch-up allowance.
- Maxing out early without checking the employer’s matching schedule.
- Confusing the 401(k) contribution deadline with the later IRA contribution deadline.
For ordinary payroll-based employee deferrals, 2026 contributions generally must come from compensation associated with the 2026 calendar year.
Employer contributions and certain self-employed arrangements can follow different timing rules.
I suggest reviewing year-to-date contributions before the final payroll periods rather than discovering problems after the year ends.
Final Thoughts on 401k Limits 2026
The 401k Limits 2026 give eligible workers more room to build retirement savings. With the standard employee limit reaching $24,500 and catch-up opportunities extending as high as $11,250, understanding the rules can make a meaningful difference.
The right contribution amount depends on your income, age, employer benefits, tax situation, and other financial priorities.
My recommendation is simple: review your current contribution percentage, confirm your employer’s matching and Roth rules, and adjust your payroll elections while there’s still time to benefit from the 2026 limits.
FAQs About 401k Limits 2026
1. What is the maximum 401k contribution for 2026?
Employees under 50 can contribute up to $24,500 in 2026. Eligible workers aged 50 and older can contribute more through catch-up contributions.
2. What is the 401k catch-up contribution limit for 2026?
The standard catch-up limit is $8,000 for eligible workers aged 50 and older, while employees aged 60 through 63 can contribute an additional $11,250.
3. Can I contribute $24,500 to both a Roth and traditional 401k?
No. The $24,500 employee contribution limit applies to the combined total of traditional and Roth 401(k) elective deferrals.
4. What is the total 401k contribution limit with employer matching in 2026?
The combined employee and employer contribution limit is generally $72,000, excluding eligible catch-up contributions and subject to compensation limits.
5. When is the deadline for 2026 401k contributions?
Regular employee salary deferrals generally must be made through eligible 2026 payroll. Employer contributions and certain self-employed plans may have different deadlines.
Ethan Caldwell is a business research writer with 9+ years of experience covering entrepreneurship, market trends, business strategies, and industry insights. He focuses on creating clear, data-informed articles that help readers understand modern business concepts.